
The financial impact of the March 2026 UAE floods, which generated significant insured losses across the market, continued to be felt in the second quarter as the full effect of the event became visible in company financials, including reinstatement premiums following the initial recognition of losses on maximum retention, according to Badri Consultancy.
Even so, the sector absorbed these losses while sustaining its growth trajectory, reinforcing the positive path established through 2025 and the increasingly broad-based nature of the industry’s performance, according to a new report on UAE-listed insurers.
Stay up to date with the latest news. Follow KT on WhatsApp Channels.
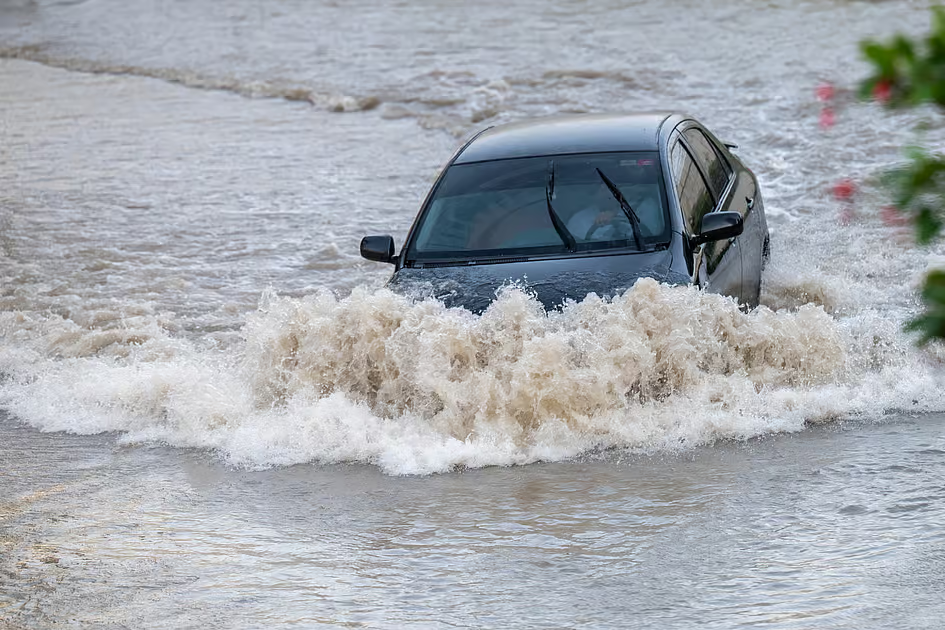
Heavy rains and thunderstorms hit the UAE in March 2026, prompting public-sector entities to allow employees to work from home due to flooding. Roads were closed, and inter-emirate transport services were also temporarily suspended because of the heavy rains.
Profits
According to the Dubai-based consultancy’s first-half data, insurance revenue for the UAE’s 27 listed insurers rose 14 per cent to Dh28 billion in H1 2026, up from Dh24.6 billion in H1 2025, reflecting sustained premium growth across both conventional and Takaful operators.
The top five insurers continued to anchor the market with Dh18.8 billion in revenue, up 12 per cent, but mid-sized and smaller insurers outpaced their larger peers, growing 19 per cent to Dh9.2 billion – pointing to a steady broadening of industry momentum beyond the market leaders.
Insurance service results, a measure of technical profitability, improved 13 per cent to Dh1.8 billion, up from Dh1.6 billion a year earlier. The gain was most pronounced among smaller operators, whose combined results rose 29 per cent year-on-year to Dh470 million, compared with a more measured 9 per cent increase to Dh1.37 billion for the top five. The report said underwriting pressure remains concentrated among a small group of insurers rather than being a market-wide concern.
The consultancy noted that profit before tax rose 13 per cent to Dh2.4 billion, with the top five contributing Dh1.8 billion, up 11 per cent, while the remaining companies delivered stronger relative growth of 20 per cent to Dh665 million.
Investment income
Investment income also advanced, up 13 per cent to Dh1.4 billion, though the gain was uneven: the top five recorded a 26 per cent increase while the remaining insurers saw a 5 per cent decline.
Takaful players, despite representing just 10 per cent of listed-sector revenue, recorded 16 per cent revenue growth and 51 per cent profit growth, outperforming conventional insurers’ 14 per cent and 10 per cent growth, respectively.
Capital adequacy and solvency remain a key regulatory focus. While most companies continue to maintain comfortable positions, a small number remain below or close to the Central Bank of the UAE’s 100 per cent solvency threshold and will require ongoing management attention and, in some cases, capital strengthening measures. Solvency outcomes varied widely across the market, reflecting divergent capital profiles that persist within the sector.
Looking ahead, it said, the industry enters the remainder of the year from a position of underlying strength, supported by healthy revenue growth, improving technical performance and a favourable overall combined ratio. Companies have so far resisted the temptation to compete on price to chase market share, choosing instead to protect margins.
However, insurers have been urged to remain watchful of rising reinsurance costs following treaty renewals, inflation in motor repair costs linked to geopolitical developments, evolving regulatory expectations, and ongoing solvency management demands. The report noted that firms combining disciplined underwriting, effective claims management, prudent capital allocation and robust solvency management will be best placed to convert top-line growth into sustainable technical profitability.
Source: Khaleej Times